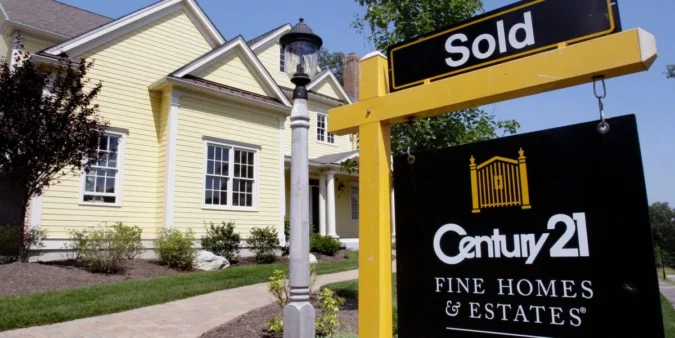
WASHINGTON, DC — Mortgage rates climbed for a third straight week, and that move landed at the same time U.S. existing-home sales slipped for a third month in a row. For buyers, the combination means borrowing costs are still rising just as the housing market remains sluggish.
Freddie Mac said the average rate on a 30-year fixed mortgage rose to 6.76% from 6.71% the week before. That was the highest level since June 26, 2025, and well above the 6.35% average from a year earlier. In a market already strained by home prices, even small rate changes can alter what households can afford.
August Home Sales Slow as Buyers Face Higher Rates and Prices
The National Association of Realtors said sales of previously occupied U.S. homes fell 2% in August from July to a seasonally adjusted annual rate of 3.98 million units. That was the third monthly drop in a row and the slowest annual pace in more than a year.
Sales also declined 1.2% from August 2025. The latest figure came in just below the 4 million pace economists had expected, according to FactSet. That gap suggests demand is still there, but many shoppers are being squeezed by the monthly cost of financing a purchase and by the prices sellers continue to ask.
Real estate markets often cool when mortgage rates rise quickly, and this year has followed that pattern. Buyers who might have moved earlier are weighing whether to wait for better financing conditions.
Why a Small Rate Move Still Matters for Monthly Budgets
The latest mortgage average may look modest on paper, but lenders and housing analysts say the impact shows up in the monthly payment. Freddie Mac said higher rates can add hundreds of dollars a month in borrowing costs and reduce a buyer’s purchasing power.
That is one reason home sales have stayed largely stagnant. When financing becomes more expensive, prospective buyers may either lower their budgets or step back from the market altogether. The 15-year fixed mortgage rate also moved higher, rising to 6.09% from 6.04% the previous week. A year ago, that average was 5.5%.
Refinancing activity can also be affected when 15-year loans move up, since those loans are often used by borrowers looking to shorten or restructure existing debt.
Inflation Picks Up Again as Gas and Wholesale Costs Rise
Housing is only one part of the pressure on household budgets. The Labor Department said consumer prices rose 3.4% in August from a year earlier, unchanged from July, but monthly inflation accelerated to 0.4% from 0.1% the prior month.
Wholesale inflation also increased. The producer price index rose 5.4% in August from a year earlier, up from 4.8% in July. On a monthly basis, producer prices climbed 0.4% after a 0.1% gain in the previous month. Those numbers point to persistent cost pressures before goods even reach shoppers.
Oil prices pushed much of the recent move. U.S. crude briefly topped $100 a barrel Thursday, and energy costs have remained sensitive to renewed fighting in the Middle East.
Diesel Above $6 Signals Pressure on Shipping and Store Shelves
Diesel prices in the United States rose past $6 a gallon on average Friday, according to AAA, hitting $6.05 compared with $5.85 the week before and $3.70 a year ago. That is an especially important number for consumers who do not buy diesel themselves but still pay for what it moves.
Diesel powers much of the freight and delivery system that brings food, packages and other goods to market. When that fuel jumps, transportation costs can rise quickly. Some businesses have already responded by adding fees to online orders and mailed packages.
Those costs can show up in households far from the oil market itself, which is why fuel spikes often ripple through the broader economy.
Jobs Data Stay Stable Even as Consumers Feel the Pinch
One bright spot in the week’s data was unemployment claims. The Labor Department said filings for jobless benefits dipped to 206,000 last week from a revised 207,000 the week before. The four-week average also edged down to 206,000.
Claims are watched as a proxy for layoffs, and the latest figures remain in a historically low range. For about a year, weekly claims have mostly stayed between 200,000 and 230,000, suggesting employers are still holding onto workers even as costs rise.
That mix can leave households in a difficult position: incomes are relatively supported, but expenses for housing, fuel and everyday goods are still elevated.
Markets End the Week with Some Relief as Oil Eases
U.S. stocks rebounded Friday after oil prices eased, even though markets still struggled to finish the week in positive territory. The S&P 500 rose and was on pace to end a four-day losing streak, while the Dow Jones Industrial Average and Nasdaq also gained.
Investors drew some comfort from the smaller-than-feared inflation reading and from a pullback in oil prices after they had climbed earlier in the week. Brent crude, the international benchmark, fell 3% to $104.42 after nearing $110 overnight.
That easing offered a temporary break, but the broader picture remained the same: higher energy costs, stubborn inflation and a housing market that is still waiting for relief.
More on what homes, rents and new builds are doing near you, on RHS Commoner.
